Buying your first home
Buy your first home
Your budget, down payment and closing costs, then viewings, your offer and getting the keys. All in one guide.
Your first purchase
Six steps from first conversation to keys.
You don’t have to know everything at the start. Take it one stage at a time.
Talk about your plans
Share your timing, preferred areas and the kind of home you picture.
Get pre-approved
A mortgage professional reviews your income, debts and down payment.
Explore and compare
View homes and neighbourhoods, then narrow the shortlist on facts.
Make an offer
Agree on price, deposit, subjects and dates that protect you.
Remove subjects
Complete inspection, financing and document review before the deadline.
Complete and move
Your lawyer or notary transfers funds and title. Then you get the keys.
Programs to ask about
A little help may be available.
Several federal and provincial programs can help first-time buyers. Each has its own rules, so check eligibility with the official source and your advisors.
- First Home Savings Account (CRA)
- Home Buyers’ Plan (CRA)
- BC first-time buyers’ transfer tax exemption (BC Government)
- GST rebates on some new homes
Your money
Down payment and mortgage
How much you need up front, and why it pays to keep some savings back.
- The minimum is 5% of the first $500,000 and 10% of the rest. Homes of $1.5 million or more need 20%.
- Your deposit counts toward the down payment once the purchase completes.
- With less than 20% down you need mortgage loan insurance, and the premium is added to your mortgage.
- Treat the minimum as a floor: keep money aside for closing costs and your first months in the home.
Example
Minimum down payment at $1,000,000
A hypothetical $1,000,000 purchase using the Government of Canada’s minimum down payment tiers.
| 5% of the first $500,000 | $25,000 |
|---|---|
| 10% of the next $500,000 | $50,000 |
| Minimum down payment | $25,000 + $50,000 = $75,000 |
| Mortgage before any insurance premium | $1,000,000 − $75,000 = $925,000 |
| Same math at $1,500,000 | 20% × $1,500,000 = $300,000 |
The premium for mortgage loan insurance would be added on top. Closing costs and lender conditions are not included.
Getting the keys
Closing costs
The money you need on top of the price, paid through your lawyer or notary on completion day.
- Property transfer tax is usually the biggest cost. Eligible first-time buyers can be exempt on the first $500,000 of homes up to $835,000.
- Legal or notary fees, title search and registration.
- GST on a new home, and move-in fees for many condos and townhouses.
- Adjustments for property tax, utilities and strata fees, plus a reserve for insurance and moving.
Example
Transfer tax on a $700,000 resale
A hypothetical resale home bought for $700,000, using BC’s general rates and then the first-time buyer exemption on the first $500,000.
| 1% on the first $200,000 | $2,000 |
|---|---|
| 2% on the next $500,000 | $10,000 |
| General transfer tax | $2,000 + $10,000 = $12,000 |
| Tax on the first $500,000 (exempt if eligible) | $2,000 + 2% × $300,000 = $8,000 |
| Tax left for an eligible first-time buyer | $12,000 − $8,000 = $4,000 |
This assumes the full exemption applies and fair market value equals the price. Legal fees, GST and adjustments are not included.
Homes for sale
Homes for first-time buyers
Stone Group Listings under $600,000.
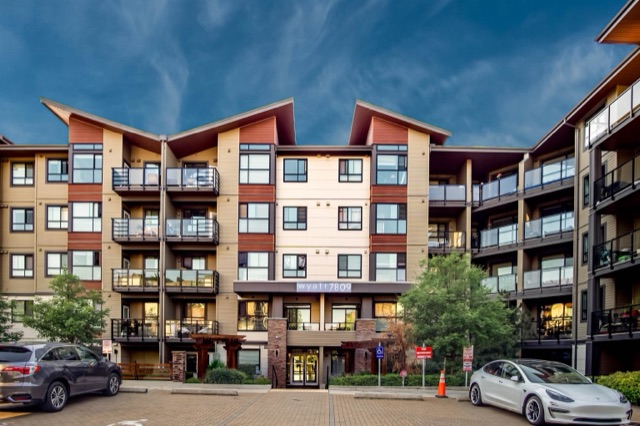 Langley39 photos
$549,900
- 2 bd
- 2 ba
- 850 sq ft
312 7809 209 Street
Willoughby Heights · Condo
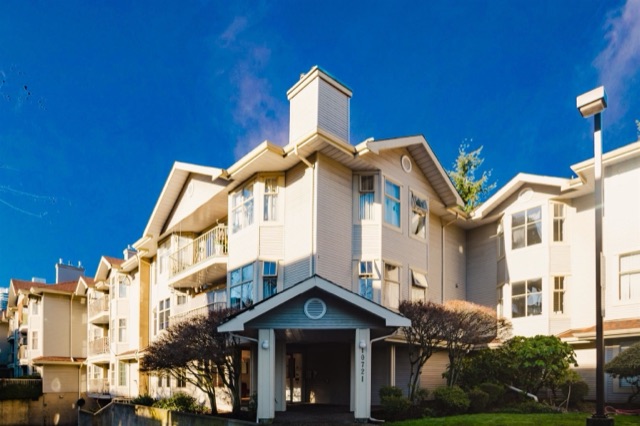 Surrey16 photos
$529,900
- 2 bd
- 2 ba
- 1,181 sq ft
204 10721 139 Street
Queen Mary Park · Condo
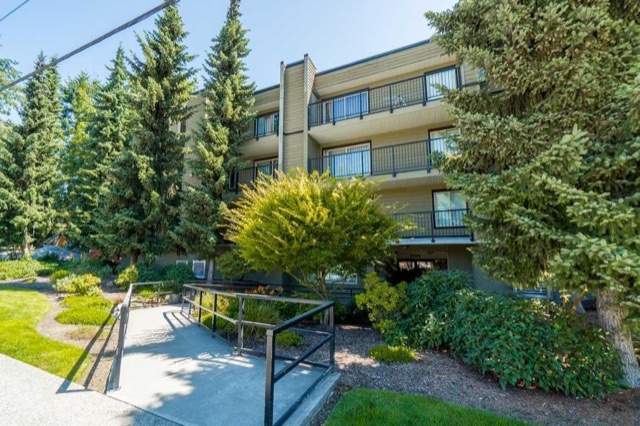 Surrey7 photos
$449,000
- 2 bd
- 1 ba
- 860 sq ft
107 10468 148th Street
Guildford · Condo
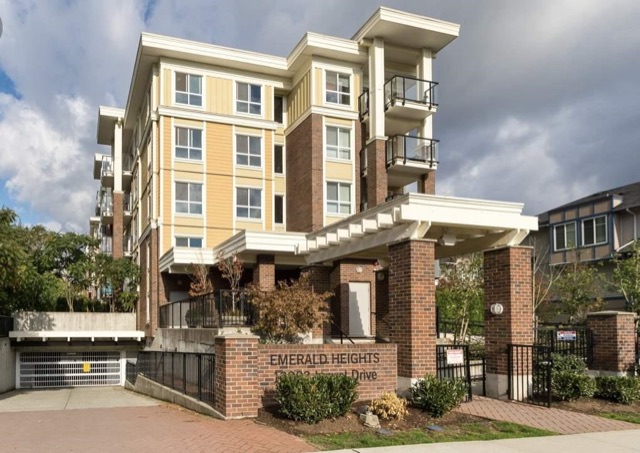 Surrey9 photos
$399,999
- 1 bd
- 1 ba
- 535 sq ft
717 13883 Laurel Drive
Whalley · Condo
At your pace
Common questions
Short answers to what first-time buyers ask us most.
Official sources (7)
General information only, not legal, tax or financial advice. Confirm the details for your purchase with the official source and your own professionals.
- Government of Canada: Saving for a down payment
- BC Financial Services Authority: Consumer guide to deposits
- CRA: Participating in your FHSAs
- CRA: What is the Home Buyers’ Plan
- Province of BC: Property transfer tax
- Province of BC: First time home buyers’ program
- BC Land Title and Survey Authority: Find information on a title
How much do I need for a down payment?
The minimum depends on the purchase price, and less than 20% usually means mortgage default insurance. The down payment calculator shows the minimum for a price you choose.
Does my deposit count toward the down payment?
Yes. BC’s real estate regulator says that once the deal completes, the deposit is added to the rest of your down payment.
When do I need mortgage loan insurance?
The Government of Canada says you need it when your down payment is less than 20% of the price. It lists premiums from 0.6% to 4.5% of the mortgage amount.
Can I use my FHSA and RRSP for the down payment?
Both can help if you meet CRA’s conditions. Ask your lender how they verify registered-account withdrawals and how long the money takes to arrive.
Does a first-time buyer pay no transfer tax?
Not always. BC exempts the tax on the first $500,000 of value for eligible buyers of homes up to $835,000. Tax on value above $500,000 is still payable. See our buyer programs guide.
What should I budget beyond the price?
Plan for taxes where applicable, legal costs, adjustments, insurance, moving, and a reserve. Your deposit is generally credited toward the purchase; do not count it twice. See the closing-cost guide.
Do I need pre-approval before we talk?
No. We can help you understand where to start. A mortgage professional should confirm your borrowing position before you make a financial commitment.
Could a presale be my first home?
Possibly. Compare deposit timing, future mortgage qualification, and completion uncertainty with an existing home. Compare the two routes.
Can I buy with a family member?
Yes, but agree how ownership, costs and a future sale will work. Your lawyer can explain the options for holding title together.